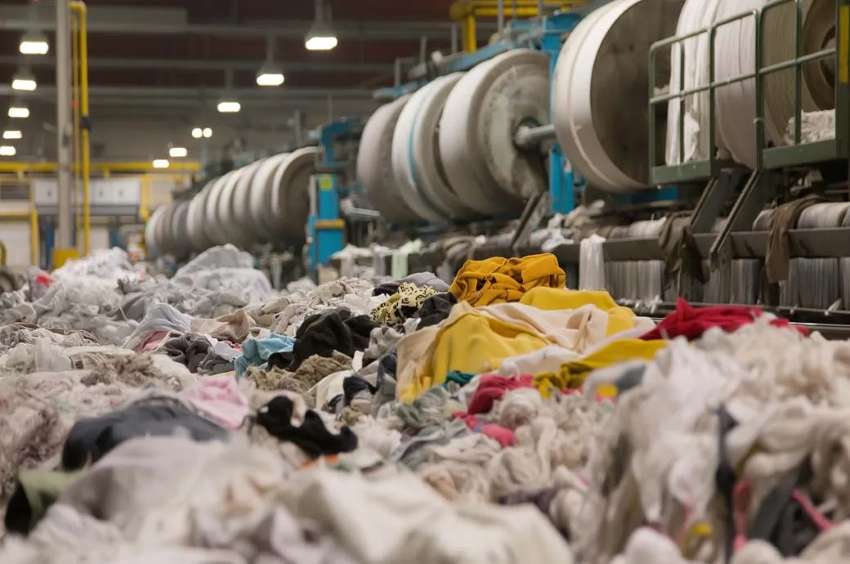
The global textile industry is discovering a hard limit to circularity: technology is advancing faster than finance. Only three of 13 textile-to-textile recycling technology archetypes can currently attract commercial project debt on standard terms, according to Systemic Bankability of Textile-to-Textile Recycling, published by Accelerating Circularity and authored by Responsible Leadership Fellow Olga Melekhina with support from ESMT Berlin. The assessment evaluates 13 technology configurations against 12 risk factors. Its major finding is stark: the closer a process gets to genuinely recycling post-consumer garments back into fibre, the harder it becomes to finance.
The problem is no longer whether recycling chemistry works in a lab. It is whether lenders can price feedstock, technology, operating performance and offtake risks over the 10-15-year life of an industrial asset.
Bankability stops at scrap
The three routes without fatal red flags are mechanical recycling of post-industrial cutting scrap, mechanical recycling of post-consumer textiles and industrial polyamide-6 depolymerisation. Their commercial maturity, however, masks a limitation: they cover only a small share of the waste stream.
Industrial nylon-6 recycling, including established operations such as those of Italy's Aquafil, relies heavily on relatively clean feedstocks like fishing nets, carpet yarns and pre-consumer polymer rejects. It is just 0.4 per cent of separately collected textile waste.
Mechanical recycling of post-consumer garments has a larger addressable market, but tearing and carding shorten cotton staple length from around 26 mm in virgin fibre to about 15 mm. Tensile strength can fall by as much as 30 per cent, limiting recycled content in commercial blends to roughly 20-30 per cent. Its addressable share is estimated at 6.6 per cent. The chemical technologies capable of producing virgin-quality inputs from more complex textile waste therefore remain trapped between venture capital and conventional infrastructure finance.
Table: Textile recycling scalability vs. technological risk
|
Technology archetype |
Maturity |
Addressable post-consumer share |
Red risk factors |
|
Mechanical—post-industrial |
TRL 9 |
Factory scrap |
0 |
|
Mechanical—post-consumer |
TRL 9 |
6.60% |
0 |
|
Polyamide depolymerisation—industrial |
TRL 8–9 |
0.40% |
0 |
|
Thermo-mechanical—sorted mono |
TRL 8 |
3.50% |
1 |
|
Polyester depolymerisation—solvolytic |
TRL 4–7 |
5.50% |
1 |
|
Polyester depolymerisation—enzymatic |
TRL 4–7 |
5.50% |
2 |
|
Polyester molecular regeneration |
TRL 5–7 |
5.50% |
2 |
|
Cellulosic regeneration |
TRL 7–8 |
12.50% |
3 |
|
Automated sorting/pre-processing |
TRL 7–8 |
Infrastructure |
3 |
|
Blend separation—hydrothermal |
TRL 6–7 |
3.70% |
4 |
|
Blend separation—cellulose removal |
TRL 5 |
3.70% |
7 |
|
Thermo-mechanical—blended input |
TRL 6 |
3.50% |
8 |
|
Polyamide depolymerisation—garments |
TRL 6–7 |
0.40% |
8 |
Source: Accelerating Circularity Systemic Bankability Report
Europe’s feedstock problem
Even before recycling plants are financed, Europe faces a feedstock bottleneck. Across Belgium, Germany, the Netherlands, Poland, Spain and the UK, about 2.116 million tonnes of post-consumer textiles are separately collected annually. Only 673,000 tonnes, or 32 per cent, falls into the low-value/non-rewearable stream targeted for industrial recycling. Just 23 per cent of that fraction is technically suitable for fibre-to-fibre processing. The cost of sorting has also deteriorated. European sorters have subsidised manual separation through exports of higher-value secondhand clothing. Falling resale prices, rising labour costs and declining garment quality have eroded that model, contributing to the insolvency of Soex in Germany and restructuring at Texaid's German subsidiaries. Even automated sorting has struggled. Sysav's 24,000-tonne optical sorting facility in Malmö, built by Stadler and Tomra, ceased operations and was sold to a real estate group.
Policy fragmentation compounds the problem. France, the Netherlands, Hungary and Latvia have operating EPR systems, while Spain, Sweden and Germany remain at different stages of implementation. France shows the funding gap: Refashion's EPR system pays €268 per tonne for sorted textiles against processing costs of about €304, leaving a €36 shortfall.
The €1,530 cost penalty
For chemical polyester recycling, costs remain particularly challenging. Collection, sorting and feedstock preparation account for about €820 per tonne. Depolymerisation, monomer purification and repolymerisation add another €1,610, taking the delivered recycled polyester cost to approximately €2,480 per tonne. Comparable virgin polyester from Asian petrochemical producers costs around €950 per tonne. The recycled alternative therefore carries a €1,530-per-tonne gap, or a 2.6-times cost multiple.
Without binding recycled-content requirements, brands have little incentive to sign take-or-pay contracts at such premiums. Letters of intent and sustainability partnerships may demonstrate demand, but they do not provide lenders with contracted cash flows. The problem then moves down the value chain. Brands buy finished garments, not polymers, leaving spinners, knitters and weavers to absorb inventory and conversion risks.
First plants carry the biggest risk
The financing problem is particularly acute for first-of-a-kind plants. Traditional project finance depends on EPC contractors guaranteeing throughput, yield and uptime through turnkey contracts, performance bonds and liquidated damages. Emerging chemical recycling plants have none of these protections at scale.
Technology developers cannot demonstrate long operating histories on contaminated post-consumer textiles. Insurers consequently hesitate to underwrite technology-performance risk. EPC contractors are reluctant to guarantee chemistry they did not develop, while technology licensors often lack the balance sheets required to support large debt packages.
Seven major chemical routes carry fatal performance-risk exposure. The experience of Renewcell reveals the consequences. Their 60,000-tonne Swedish plant reached commercial scale but collapsed after anticipated brand demand failed to translate into binding orders. Relaunched as Circulose under Altor, the business has shifted towards contracted supply agreements with Tangshan Sanyou, Aditya Birla and Jilin Chemical Fiber, alongside direct retail commitments.
Carbios faces a similar financing challenge with its Longlaville enzymatic PET project in France. Despite public grants, an Inditex partnership and individual lender approvals, the company said in August 2026 that its financial close had been delayed by prolonged due diligence over technology-risk allocation.
In contrast, many US projects are locating near established industrial infrastructure. Syre is commissioning a 10,000-tonne facility in North Carolina with supply partnerships including Nike, while Eastman's 110,000-tonne Kingsport methanolysis plant benefits from mature chemical infrastructure, although its feedstock remains primarily post-consumer packaging.
De-risking the missing middle
The report highlights that grants alone will not solve the financing deficit. Capital subsidies lower construction costs but do not eliminate uncertainties around feedstock, technology performance or offtake. Public institutions therefore need to absorb part of the risk that commercial lenders cannot yet price.
One route is public first-loss guarantees for first-of-a-kind plants, similar to mechanisms used in geothermal and other high-risk infrastructure. Under the EU Clean Industrial Deal State Aid Framework, public-backed structures could potentially support commercial lending by absorbing an initial portion of project losses.
The second is binding advance market commitments. Fashion brands could pool purchasing volumes into long-term take-or-pay contracts, replicating models used in carbon removal and emerging bio-based industries.
The third is a financing-grade feedstock standard. Existing certifications such as the Global Recycled Standard establish chain of custody but do not adequately specify chemical purity, moisture, elastane content or contaminants. A textile equivalent of Europe's EN 643 recovered-paper classification could turn heterogeneous textile waste into a contractable industrial commodity.
The circular textile economy therefore faces a paradox: the technologies capable of solving the industry's hardest waste problem are the least capable of securing conventional capital. Until public guarantees, contracted demand and standardised feedstock markets close that gap, textile-to-textile recycling will remain rich in pilots but poor in bankable plants.