
FW
Soft wholesale demand, price cuts test Under Armour restructuring strategy
Under Armour’s multi-year operational turnaround is confronting severe market pressures as cautious retail spending and heavy industry promotions suppress sales. In Q2, FY27, the Baltimore-based sportswear maker reported a 7 per cent decline in quarterly revenue to $1.2 billion, weighed down by weak traffic in core retail channels and high promotional activity across North America. The contraction was visible across major segments, with footwear falling 11 per cent to $234 million and apparel slipping 6 per cent to $880 million.
Margin compression drives operational realignment
Sluggish full-price sell-through forced gross margins down 30 basis points to 47 per cent, as management navigated elevated discounting, channel mix headwinds, and persistent global supply chain expenses. To defend profitability, Under Armour is advancing a comprehensive $305 million restructuring program aimed at eliminating SKU complexity and stream-lining corporate overhead.
Product innovation key to regaining market share
With direct-to-consumer revenues declining by 8 per cent and digital sales sliding 12 per cent, brand executives are pivoting toward disciplined inventory control and premium product launches. Expanding performance running lines and high-tier athletic gear remains vital to restoring brand heat and winning back shelf space in international markets.
Targeting efficiency across multiple categories
Founded in 1996, Under Armour manufactures performance apparel, footwear, and accessories. Key markets center on North America, EMEA, and Asia-Pacific. Generating over $5 billion annually, the brand’s restructuring plan targets multi-category operational efficiency, premium supply chain alignment, and sustainable growth across global athletic retail by FY27.
Global cotton consumption to outpace production in 2026-27: ICAC
A widening global supply gap is failing to trigger the expected commodity price rally across international textile markets. The International Cotton Advisory Committee (ICAC) projects, global cotton consumption to outpace production by 353,000 tons in the 2026–27 season, moving the sector from surplus into deficit as world output contracts 4 per cent to 25.75 million tons. Despite this physical shortfall, international pricing benchmarks like the Cotlook A Index declined by 3.75 per cent heading into November.
Downstream demand stagnation pressures spinners
The paradox stems directly from sluggish consumer spending across major Western clothing markets, where elevated interest rates and cautious consumer behavior continue to limit re-orders. Spinning mills in China, India, and Vietnam are operating under tight margin pressure, purchasing raw fiber strictly on a hand-to-mouth basis to avoid holding costly inventory.
Synthetic substitution accelerates price erosion
Compounding the pricing pressure is the ongoing shift toward cheaper synthetic yarns. Global garment brands are actively replacing pure cotton lines with recycled polyester and man-made fiber blends to cut input costs. Until global apparel retail sales regain momentum, raw cotton prices will remain detached from supply deficit fundamentals.
Focusing on sustainable farming and supply chain traceability
Operating at the intersection of agriculture and apparel manufacturing, the cotton industry supplies global textile mills with natural lint. Key markets span major producers like Brazil and the US alongside consuming hubs in Asia. Sector growth plans center on sustainable farming and supply chain traceability, supported by stable long-term demand despite current margin pressure.
Bangladesh shifts focus to MMF and technical textiles
The world’s second-largest clothing supplier, Bangladesh plans to replace basic cotton garments with high-margin synthetics and performance textiles. While ready-made garments currently drive 81 per cent of total national exports, basic cotton items like t-shirts keep factory margins tightly compressed. Sourcing dynamics are rapidly shifting, forcing domestic textile manufacturers to invest heavily in synthetic yarn spinning, recycled polyester, and functional outerwear.
Value addition over low-margin volume
Relying on basic garments capping cut-and-make charges at lower levels limits long-term growth. Industry analysts project, shifting factory capacity toward activewear, outerwear, and man-made fiber (MMF) blends can increase manufacturing value margins two to three times over basic cotton lines.
Localizing fabrics to cut lead times
Importing specialty synthetic fabrics from China and India inflates operational costs and extends delivery schedules. To retain price advantages ahead of Bangladesh's upcoming Least Developed Country (LDC) status graduation, local manufacturers are vertically integrating knit and woven supply chains. Upgrading domestic mill technology reduces raw material imports, compresses lead times, and stabilizes supply chains for global buyers.
Industrial capacity and high-value growth plans
Bangladesh's RMG sector manufactures bulk cotton knits, structured tailoring, activewear, and eco-friendly denim. Serving the EU and US, the sector generates nearly $39 billion annually. Industry initiatives focus on expanding synthetic mill infrastructure to achieve $100 billion in garment exports by 2030.
Ghana champions apparel-led export diversification strategy
West African textile manufacturing is gaining momentum as trade corridors expand toward Caribbean and Western markets. Under targeted industrial initiatives - including dedicated apparel enclaves like the 2,000-acre Dawa Industrial Zone - Ghana is positioning finished garments as primary economic drivers rather than domestic retail commodities.
Strategic value addition
Official export performance data underscores a structural transformation; Ghana recorded over $61.8 million in textile exports while drawing GHS 15.42 billion in tourism revenue. Elevating local fashion ecosystems into structured industrial supply chains directly expands employment and high-value foreign exchange, states Kwasi Kyei Darkwah, Special Envoy to the Caribbean Region.
Supply chain re-alignment
While raw cotton processing infrastructure matures in the Eastern region, local producers still struggle with technical skill gaps and raw material import dependencies. Commercial scaling depends heavily on securing long-term transatlantic procurement agreements to sustain workforce expansion across regional manufacturing hubs.
West Africa apparel hub overview
Ghana’s textile sector manufactures traditional woven prints, ready-to-wear apparel, and specialized technical fabrics. Concentrated in West Africa with expanding duty-free export channels to the US and EU, the industry targets scalable industrial park expansion. Operating since the mid-20th century, recent fiscal reforms aim to restore historical export prominence.
Footfalls across Tiruchi T&A showrooms decline amid elevated costs and shifting consumer behavior
Textile and apparel showrooms across Tiruchi’s commercial hubs - including NSB Road and Singarathope - are navigating a sharp decline in festive and seasonal footfalls. Footfalls in traditional multi-storey flagship outlets contracted by 20 per cent to 25 per cent this season as elevated living costs, unseasonal weather events, and shifting consumer behavior curtailed discretionary spending. Industry data indicates, while national domestic apparel demand is targeted to hit $250 billion by 2030, Tier-II offline retail corridors are experiencing localized margin pressures. Suburban consumers increasingly opt for neighborhood readymade stores or quick-commerce platforms rather than visiting central market districts.
Strategic modernization and direct-to-consumer adaptations
To counteract subdued store traffic, major regional retailers are recalibrating operations toward omnichannel models and fast-fashion inventory management. High footfall volume is no longer guaranteed by location alone; retail survival now hinges on rapid inventory turnover, hyper-local marketing, and optimized digital engagement, notes S Ramanathan, Senior Vice President, Regional Textile Traders Association. Modern outlets are integrating direct-to-consumer delivery services and curated value collections to preserve market share against aggressive online discounts.
Retailing strategy and regional expansion
Tiruchirappalli Textile Merchants Enterprise is a regional retail operator specializing in traditional silk sarees, ethnic wear, and daily readymade apparel across Central Tamil Nadu.
Founded in 1984, the firm operates large-format showrooms aimed at family demographic segments. The enterprise aims to expand its suburban store network while targeting steady mid-single-digit revenue growth amidst evolving consumer shopping patterns.
Apparel retailers prune product lines to free up cash
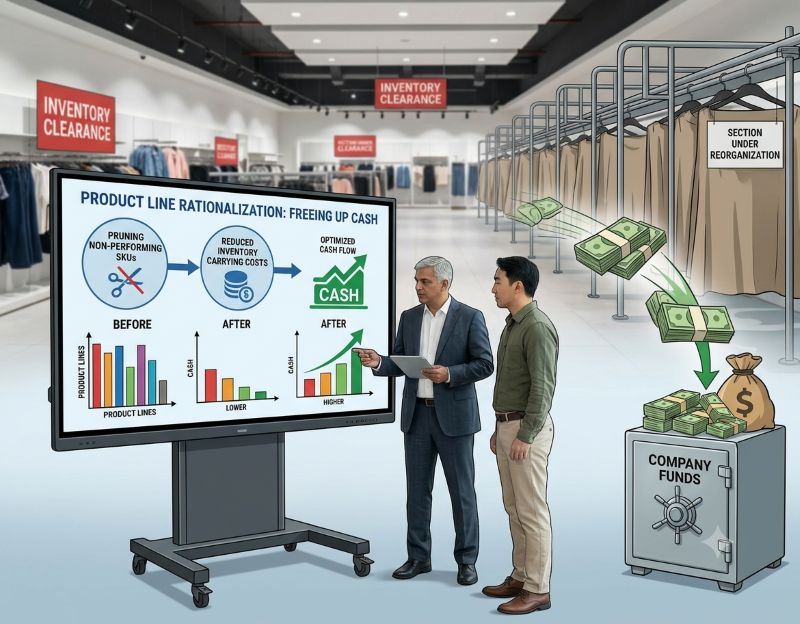
Apparel brands are cutting product complexity to protect margins, reduce inventory risk and improve cash generation. After years of expanding assortments to capture every consumer segment, retailers are discovering that excessive choice can weaken profitability without delivering proportionate sales growth.
Industry benchmarking suggests that the bottom 30-40 per cent of stock-keeping units (SKUs) across apparel and footwear generate less than 5 per cent of gross commercial revenue while absorbing more than 25 per cent of working capital and design resources. These marginal products add costs across sampling, sourcing, manufacturing, warehousing and markdowns, often without generating meaningful demand.
The shift towards smaller, more focused collections reflects mounting pressure from subdued discretionary spending, higher logistics costs and persistent promotional activity. Instead of multiplying styles, colours and seasonal variations, brands are concentrating resources on proven sellers and distinctive products that command stronger full-price realisation.
Brands cut back
The reset spans mass-market sportswear, denim and luxury fashion. Under Armour has reached an initial target of reducing its SKU count by 25 per cent and is pursuing a further 25 per cent reduction across its collections. The strategy prioritises product productivity and full-price sales over indiscriminate assortment expansion.
Levi Strauss for example, is concentrating on established denim franchises, including the 501, while reducing slow-moving style and colour variations. Lululemon has cut assortments in North American stores by 15 per cent, seeking to simplify store operations, improve replenishment and eliminate redundant inventory.
Luxury brands are following the same logic. Gucci has reduced its product range by approximately 20 per cent, refocusing on core leather goods and premium wardrobe staples. Burberry, under chief executive Joshua Schulman, is narrowing seasonal assortments around outerwear, scarves and its signature trench coats.
Hugo Boss has also made product simplification a central part of its Claim 5 strategy, targeting a 20 per cent reduction in collection complexity by 2028. The objective is to improve inventory productivity, strengthen profitability and generate more free cash flow.
Table: Catalog rationalisation benchmarks
|
Brand |
Assortment strategy |
Primary objective |
|
Under Armour |
Targeting cumulative 50% SKU reduction |
Improve full-price sales and margins |
|
Hugo Boss |
20% reduction in collection complexity by 2028 |
Increase free cash flow and operating earnings |
|
Lululemon |
15% SKU reduction in North American stores |
Improve store efficiency and replenishment |
|
Gucci |
Approximately 20% range contraction |
Strengthen brand identity and core categories |
|
Burberry |
Narrower seasonal assortments |
Concentrate sales on outerwear and heritage products |
The cost of complexity
Every additional SKU creates costs beyond its manufacturing price. Product development requires technical specifications, pattern-making, fit approvals, sampling, fabric commitments and merchandising support. Once products enter the supply chain, each variation adds forecasting requirements, warehouse locations, inventory tracking and replenishment decisions.
Industry estimates put the incremental development and administrative carrying costs of introducing a SKU at $3,000 to $10,000 before it reaches the retail floor. While the precise cost varies by product and business model, the underlying economics are clear: low-volume styles can consume disproportionate resources.
Fragmented assortments also weaken purchasing power. When orders are spread across numerous designs, colours and fabric specifications, sourcing teams struggle to secure volume discounts from mills and factories. Smaller production runs can increase unit costs, complicate quality control and extend lead times.
The problem continues at the point of sale. Too many similar products can blur brand positioning and make purchasing decisions harder. When demand fails to meet forecasts, retailers resort to markdowns to clear stock, eroding margins and tying up capital that could have supported replenishment of stronger sellers.
Reducing assortment breadth allows brands to concentrate buying volumes behind validated products. Larger production runs can improve sourcing terms, while simpler inventory structures support faster replenishment and better stock visibility.
Hugo Boss’s margin play
Hugo Boss shows how assortment discipline can support a broader financial reset. Through its Claim 5 programme, the German fashion group is working towards reducing collection complexity by 20 per cent by 2028, alongside its wider profit and cash-generation targets.
The company’s approach focuses on strengthening core product categories, improving sourcing efficiency and reducing dependence on promotional sales. Gross margin grew by 200 basis points to 64.9 per cent, while group inventories declined 15 per cent year on year. The business also generated over €100 million in quarterly free cash flow.
These results underline the potential benefits of tighter assortment management, although margin performance also depends on pricing, product mix, demand and promotional intensity. SKU reduction alone does not guarantee a turnaround.
For Hugo Boss, the objective is to direct capital towards products with stronger commercial potential rather than maintaining an expansive range for its own sake. A more disciplined collection can improve inventory turnover and cash conversion while reinforcing the brand’s core positioning.
Precision over breadth
The industry’s assortment reset marks a shift away from the assumption that more products automatically produce more sales. Retailers are evaluating collections by their contribution to revenue, gross margin, inventory turns and working-capital efficiency.
The challenge is to remove unproductive complexity without sacrificing innovation or consumer relevance. Excessive pruning can leave gaps in sizes, price points and customer needs, while overdependence on a narrow group of bestsellers can increase concentration risk.
Brands must therefore distinguish between commercially redundant options and products that serve a clear strategic purpose. Better demand forecasting, SKU-level profitability analysis and faster replenishment can help merchandising teams make that distinction.
For apparel businesses operating under tighter margins, assortment discipline is becoming a competitive tool. The priority is no longer to offer the largest possible range, but to build collections that sell through efficiently, support brand identity and generate stronger returns on invested capital.
Kering deploys brand-level line extensions as luxury brands recalibrate retail strategies
Luxury conglomerates are recalibrating retail strategies across Greater China, prioritizing high-margin hard luxury and specialized accessories over volume-driven leather goods. Showcasing this portfolio shift at the Shanghai expo, Kering deployed brand-level line extensions - including Qeelin’s Bajin fine jewelry series and specialized optical models from Lindberg - to capture resilient high-net-worth demand amidst broader market stabilization.
Hard luxury and accessories drive premium realizations
Shifting buyer behavior across Asian retail corridors has accelerated demand for enduring, heritage-backed investment pieces over seasonal fashion. Kering Eyewear and fine jewelry lines achieved elevated gross margins by targeting niche consumer segments with localized cultural design cues. Arthur Chen, Retail Strategist noted, European fashion houses are restructuring regional assortments toward entry-level luxury accessories and high-value fine jewelry to buffer against fluctuating foot traffic in tier-one Chinese cities
Localized product strategy offsets regional demand friction
However, global luxury groups face ongoing headwinds from cautious middle-class discretionary spending and shifting luxury import dynamics across Asia-Pacific. To navigate these market realities, apparel and accessory houses are scaling bespoke retail services, regional designer residencies, and exclusive capsule debuts. By integrating localized design motifs into global brand lines, luxury portfolios aim to protect regional market share and drive long-term customer lifetime value.
High-end heritage brand portfolio
Kering manages a global portfolio of luxury fashion, leather goods, jewelry, and eyewear houses, including Gucci, Saint Laurent, Bottega Veneta, and Balenciaga. Generating €14.7 billion in revenue with 44,000 employees globally, the group expands high-margin eyewear and fine jewelry categories while deepening strategic retail footprint across core Asian luxury markets.
Pearl Global Industries expands footprint as revenue rises by 31.1% Y-o-Y in H1FY 27
Global fashion retailers are increasingly shifting order allocations toward multinational supply vendors to mitigate geopolitical risks and tariff uncertainties. Leveraging this structural migration, Pearl Global Industries expanded its multi-country production footprint, delivering record first-half financial performance for FY27. Consolidated half-yearly revenue reached Rs 3,330 crore, representing a 31.1 per cent Y-o-Y increase, while profit after tax increased by 63.6 per cent to Rs 225 crore. Total volume shipments expanded to 43.6 million units, driven by strong seasonal order execution across western retail markets.
Operational scaling drives margin gains
Expanding production scale across low-cost hubs has allowed major vendors to capture higher operating efficiencies while maintaining product agility. Pearl Global’s adjusted EBITDA margin reached a record 10.5 per cent during the period, benefiting from favorable product mix shifts toward complex woven garments and outerwear. Sarah Jenkins, Sourcing Director, notes, global apparel buyers are actively prioritizing suppliers capable of balancing nearshore flexibility with large-scale Asian manufacturing capacity. To capitalize on expanding vendor consolidation, the company operationalized a new garment facility in Bangladesh, adding seven million pieces in annual capacity to reach a total group throughput of 108 million pieces.
Strategic capital allocation targets long-term scale
However, international garment exporters continue to navigate volatile ocean freight corridors and regulatory compliance overheads across European retail markets. To address these operational friction points, fashion suppliers are committing fresh capital toward automation, sustainable laundry facilities, and digital supply chain integration. Pearl Global has outlined a capital expenditure program of Rs 675–725 crore through FY30, aiming to achieve an annual revenue milestone of Rs 9,000–10,000 crore. Strategic trade developments, including the prospective India-UK Free Trade Agreement, present long-term structural tailwinds for regional apparel exporters targeting European expansion.
Targeting Rs 10,000 crore revenue by FY30
Pearl Global Industries manufactures knitwear, denim, woven apparel, and activewear for major global fashion retailers across the United States, Europe, and Asia-Pacific. Founded in 1987, the company is advancing a Rs 725 crore expansion plan to reach Rs 10,000 crore in revenue by FY30, supported by robust double-digit EBITDA margin growth.
Ralph Lauren accelerates D2C expansion to defy luxury slowdown
While global luxury fashion conglomerates grapple with cooling consumer demand across key Western markets, Ralph Lauren Corporation is outperforming industry headwinds through systematic brand elevation and aggressive direct-to-consumer expansion. Financial results show annual revenues surpassing $8.1 billion, driven by double-digit growth in Asia and resilient full-price domestic selling.
Brand elevation outpaces sector contraction
The luxury apparel sector faces ongoing structural adjustments, yet premium positioning strategies allow top-tier brands to capture high-margin demand. Ralph Lauren raised its Average Unit Retail (AUR) by 18 per cent across its direct-to-consumer network, effectively shielding margins from freight volatility and broader inflationary pressure.
Our strategy of continuous brand elevation, disciplined promotional control, and localized market expansion allows us to drive sustainable revenue growth even in choppy economic waters, noted Patrice Louvet, CEO, Ralph Lauren Corporation.\
Regional drivers and digital monetization
Asia remains the primary operational growth vector for the retail sector, delivering over 20 per cent constant-currency revenue gains, led by strong performance in Greater China. Furthermore, digital commerce comparable sales expanded by double digits globally, demonstrating that high-end apparel consumers are increasingly engaging through integrated omnichannel ecosystems rather than traditional multi-brand wholesale channels.
Heritage lifestyle retail execution
Ralph Lauren Corporation designs, markets, and distributes premium lifestyle products—including luxury apparel, accessories, footwear, home furnishings, and fragrances—across North America, Europe, and Asia-Pacific. Founded in 1967 as a necktie line, the company maintains steady long-term financial growth targeting high-single-digit operating margins and annual revenues exceeding $8 billion.
SGCCI to establish direct supply channel for MMF and finished apparel
The Southern Gujarat Chamber of Commerce and Industry (SGCCI) finalized two strategic Memorandums of Understanding (MoUs) in Morocco to establish a direct supply channel for man-made fabric and finished apparel across North Africa and Southern Europe.
Capitalizing on duty-free trade and evolving supply chains
Following bilateral trade hitting $4 billion, Surat’s textile hub is positioning synthetic textiles, metallic yarn, and premium viscose to leverage Morocco’s duty-free access into the European Union. Surat possesses world-class production capacity, while Morocco acts as an operational gateway to European fashion houses. This alliance unlocks vital export routes for our local MSME units, states Vijay Desai, President, SGCCI. Early trade inquiries indicate strong demand for high-value technical textiles and synthetic blends.
Overcoming market barriers through institutional frameworks
While logistical bottlenecks and raw material volatility remain ongoing operational challenges for Indian exporters, institutional frameworks under these MoUs aim to streamline trade protocols and direct B2B buyer exchanges. The strategy is already showing practical success: local weaving enterprise TexSynthetics secured its initial trial order of 50,000 meters of specialized polyester fabric for Casablanca-based garment manufacturers within days of the accord.
An empowering regional enterprise
Established in 1940, SGCCI supports over 12,000 commercial members across Southern Gujarat. It primarily serves man-made textiles, apparel processing, and diamond finishing sectors. The chamber targets global export diversification to boost regional MSME growth, targeting a 15% increase in synthetic fabric exports through international trade corridors.